As a market analyst, the question I’m most frequently asked is about timing. Discerning whether is now a good time to buy property in Malaysia requires more than a simple yes or no; it demands a rigorous examination of macroeconomic signals and market-specific data.
This Malaysian property market analysis 2026 is designed to cut through the noise, providing a clear perspective for both prospective homeowners and strategic investors.
We will dissect critical factors, from interest rate trajectories to supply-demand dynamics, and evaluate the key property investment risks and opportunities that define the current landscape.
Making a multi-generational financial commitment during a period of global economic recalibration is a significant decision, and this guide is structured to equip you with the data-driven insights needed to act with confidence.
Analysing the 2026 State of the Malaysian Property Market
Pro Tip: My analysis indicates that 2026 is shaping up to be a tactical buyer’s market, particularly in specific sub-sectors and geographical locations. An oversupply in certain property segments, coupled with a stabilising interest rate environment, is creating pockets of opportunity for well-capitalised buyers. However, this is not a blanket recommendation; a granular approach is essential.
Is It a Buyer’s or a Seller’s Market in 2026?
The distinction between a buyer’s and a seller’s market is fundamental. A buyer’s market, as defined by Investopedia, occurs when supply exceeds demand, granting purchasers significant negotiating power.
Conversely, a seller’s market is characterised by high demand and limited inventory, driving prices up. Based on the latest data from Malaysia’s National Property Information Centre (NAPIC), the market in 2026 exhibits clear signs of being advantageous for buyers.
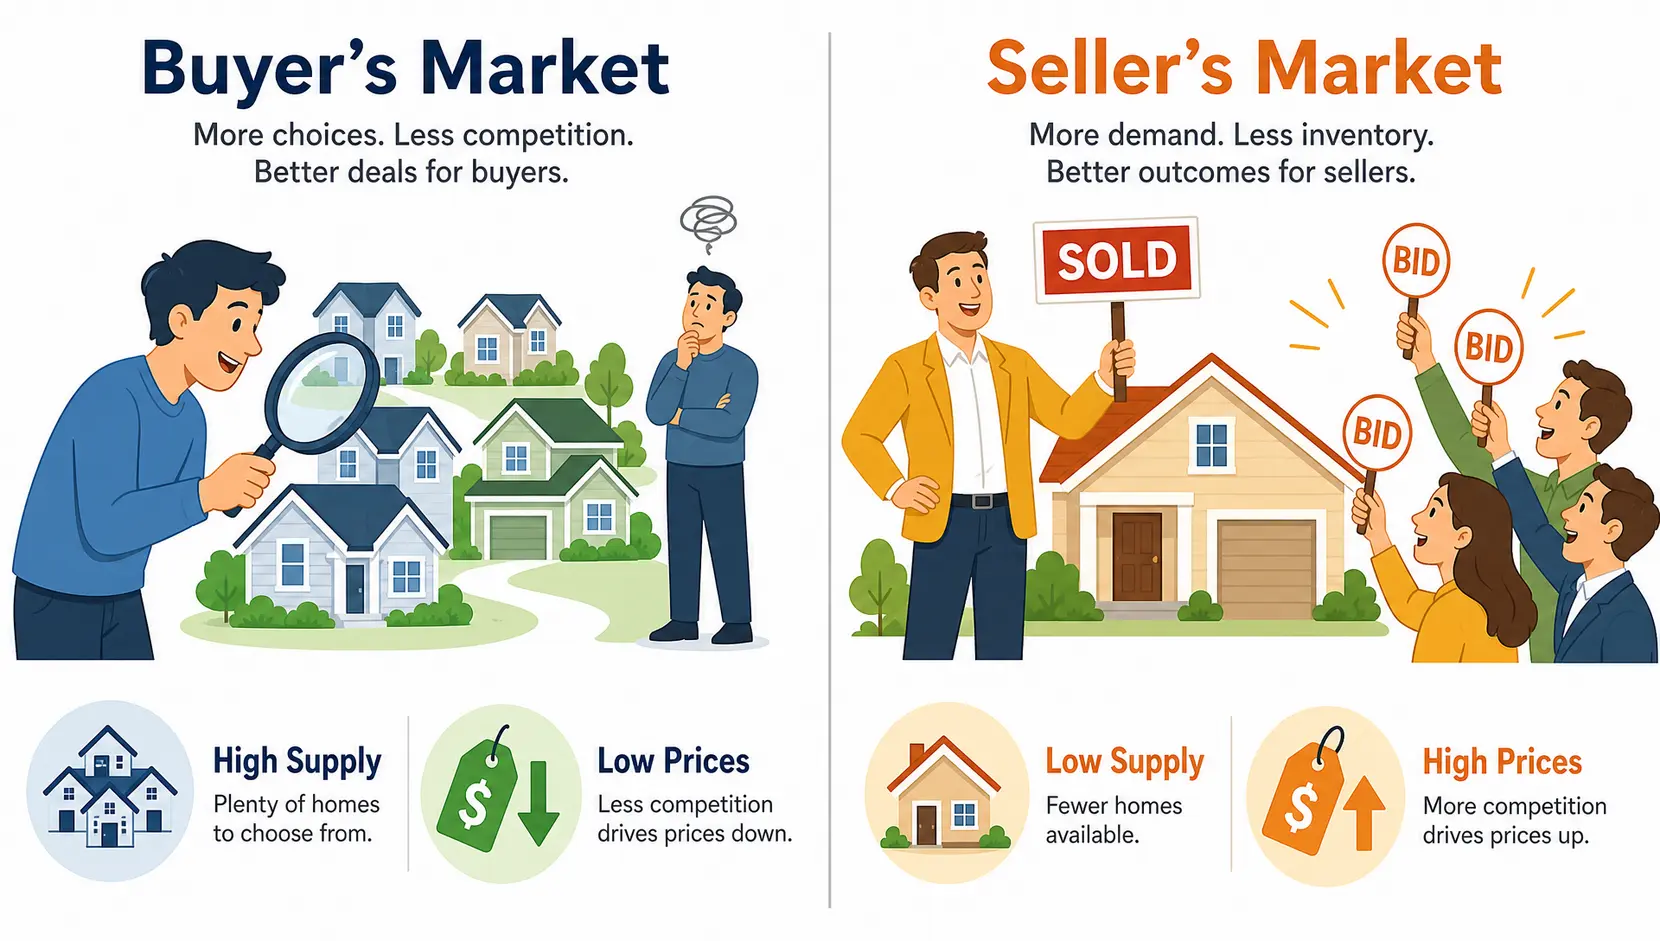
Data from the first half of 2026 points to a persistent overhang in the high-rise residential sector, especially in states like Johor and Selangor. The total number of unsold completed units, while showing a slight decrease from its peak, remains elevated.
This inventory surplus forces developers to offer more competitive pricing and attractive packages, such as subsidised legal fees and furnishing packages, to clear stock.
For a buyer, this translates directly into enhanced leverage during price negotiations and a wider selection of properties to choose from.
| Market Indicator | Buyer’s Market Characteristics (Observed in 2026) | Seller’s Market Characteristics |
|---|---|---|
| Property Supply | High inventory, significant number of unsold units (overhang). | Low inventory, few available listings. |
| Price Trend | Prices are stable or showing slow, single-digit growth. Price reductions are common. | Rapid price appreciation and bidding wars. |
| Negotiating Power | Buyers have strong leverage to negotiate price and terms. | Sellers dictate terms and often receive offers above asking price. |
| Days on Market | Properties tend to stay on the market for a longer duration. | Properties sell quickly, often within days. |
Recent Property Price Trends and Macroeconomic Forecasts
The Malaysian House Price Index (MHPI) has shown modest growth, hovering around 1.5% to 2.5% annually. This indicates a market that is correcting and stabilising rather than booming.
As an analyst, I see this as a healthy sign, preventing the formation of a speculative bubble. The primary macroeconomic lever influencing this trend is the Overnight Policy Rate (OPR), set by Bank Negara Malaysia (BNM).
Throughout late 2025 and into 2026, BNM has maintained the OPR at 2.75% to balance economic growth with inflationary pressures. A stable OPR translates to predictable mortgage rates, which is a crucial factor for homebuyers assessing their debt service ratio.
Andrew Wong’s Insight: “My forecast for the second half of 2026 anticipates that the OPR will likely remain on hold, barring any significant global economic shocks. The Malaysian government’s focus on stimulating domestic consumption and investment provides a buffer against aggressive monetary tightening. This period of interest rate stability presents a window of opportunity for buyers to lock in financing at reasonable costs before the next rate cycle begins.”
The Pros and Cons of Buying Malaysian Property in 2026
Summary: The decision to buy hinges on a classic risk-reward analysis. Current market conditions offer tangible benefits like negotiating power and government support. However, these must be weighed against potential volatility from both domestic policy shifts and the global macroeconomic environment.
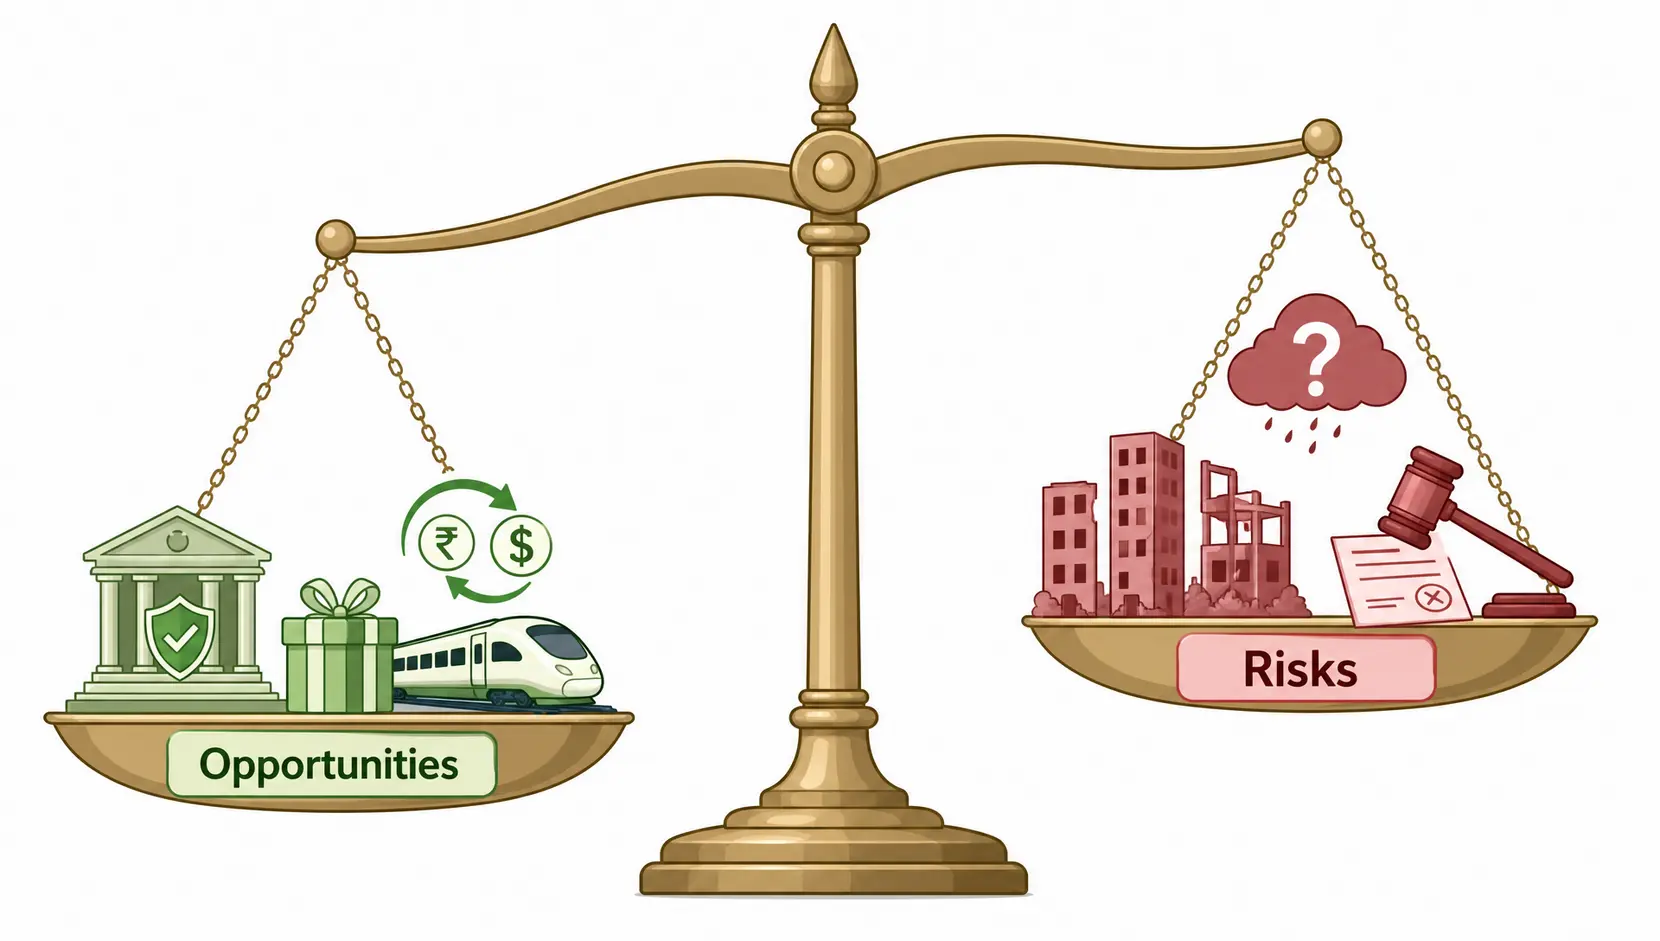
Opportunities: Why Now Could Be a Strategic Time
Several factors converge to make 2026 a potentially opportune moment for property acquisition in Malaysia.
- Government Initiatives: The government has continued to promote homeownership through various schemes. Furthermore, the revised Malaysia My Second Home (MM2H) programme, with its tiered structure (Silver, Gold, Platinum), is designed to attract foreign investment and residency, which could stimulate demand in certain market segments, particularly in designated Special Economic Zones (SEZs).
- Developer Incentives: As mentioned, the existing property overhang compels developers to be more competitive. This goes beyond mere price cuts to include absorption of stamp duty costs, extended warranties, and even rental subsidies for a limited period for investment properties.
- Infrastructure Development: Major ongoing infrastructure projects like the East Coast Rail Link (ECRL) and the Johor Bahru-Singapore Rapid Transit System (RTS) are set to enhance connectivity and unlock value in surrounding areas. Buying before these projects are completed allows investors to potentially capitalise on future appreciation.
- Favourable Currency Exchange: For international buyers, the Malaysian Ringgit (MYR) continues to offer a favourable exchange rate against major currencies like the US Dollar and Singapore Dollar, effectively creating a discount on property prices.
Risks: Potential Downsides and Systemic Headwinds
A prudent analysis must also confront the inherent risks involved in any major investment.
Risk Warning: The property market is not immune to systemic risk. A global economic downturn, escalating geopolitical conflicts, or a sudden spike in domestic inflation could lead Bank Negara Malaysia to raise the OPR. A rate hike would increase borrowing costs for variable-rate mortgages, potentially straining a homeowner’s finances and suppressing property demand.
- Persistent Overhang: While the overhang creates buyer opportunities, it also poses a risk. In areas with excessive supply, capital appreciation may be muted for several years, and securing tenants at a desirable rental yield could prove challenging.
- Economic Uncertainty: The global economic outlook for 2026 remains fluid. A slowdown in major economies like China or the United States could have knock-on effects on Malaysia’s export-oriented economy, impacting job security and consumer confidence, which are key drivers of the property market.
- Policy and Regulatory Changes: Property laws and taxes can change. Prospective buyers, especially foreign investors, must stay abreast of regulations governed by bodies like the Securities Commission Malaysia and local land offices. Unexpected changes to Real Property Gains Tax (RPGT) or foreign ownership rules could impact an investment’s profitability.
How to Decide: Is Now the Right Time for YOU to Buy Property?
Pro Tip: The ‘right time’ to buy property is less about timing the market perfectly and more about your personal financial readiness. Market conditions are secondary to your own balance sheet and long-term goals.
Key Checklist: Assessing Your Financial Health and Readiness
Before even browsing listings, a thorough self-assessment is non-negotiable. Ask yourself these questions:
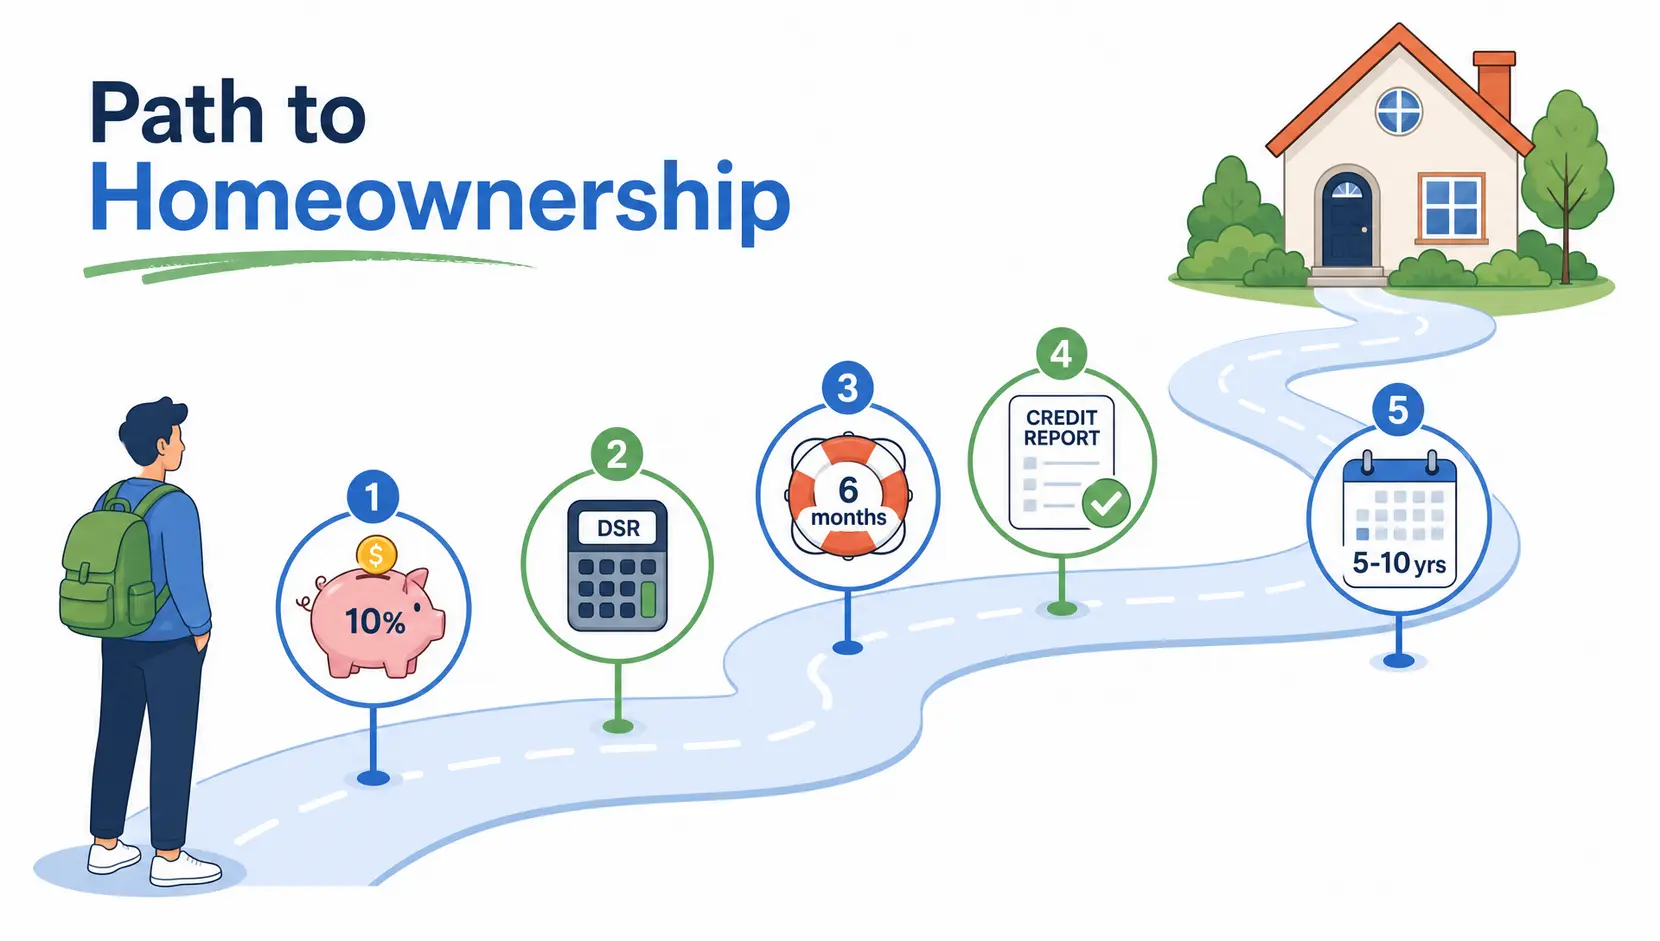
- Down Payment: Have you saved the requisite 10% down payment, plus an additional 5% for ancillary costs like legal fees, stamp duty, and valuation fees?
- Debt Service Ratio (DSR): Have you calculated your DSR? This is your total monthly debt commitments divided by your net monthly income. Most Malaysian banks require a DSR below 60-70% to approve a mortgage application.
- Emergency Fund: Do you have an emergency fund equivalent to at least six months of living expenses (including the potential new mortgage payment)? This is critical to weather any unforeseen financial shocks.
- Credit Score: Have you checked your CCRIS and CTOS reports? A clean credit history is paramount for securing favourable mortgage terms.
- Investment Horizon: Are you prepared to hold the property for the medium to long term (5-10 years)? Property is an illiquid asset, and short-term flipping in the current market is a high-risk strategy.
Strategic Differences: Buying for Own Stay vs. for Investment
Your purchasing strategy must align with your objective. The criteria for selecting a family home are vastly different from those for a rental property.
| Consideration | Buying for Own Stay | Buying for Investment |
|---|---|---|
| Primary Goal | Lifestyle, comfort, long-term stability. | Rental yield and/or capital appreciation. |
| Location Analysis | Proximity to workplace, schools, family, and amenities (parks, healthcare). | Proximity to transport hubs, universities, business districts, and areas with high rental demand. |
| Property Type | Based on family size and personal preference (e.g., landed vs. high-rise). | Driven by target tenant demographic (e.g., small units for students/young professionals, larger units for families). |
| Financial Metric | Affordability and monthly mortgage sustainability. | Gross/Net Rental Yield, Cash-on-Cash Return, and projected capital growth. |
| Emotional Factor | High. The ‘feel’ of the home and neighbourhood is crucial. | Low. The decision should be based purely on numbers and data. |
Frequently Asked Questions
1. Is it worth investing in an apartment in Malaysia in the current climate?
From an investment standpoint, apartments or condominiums require careful selection in 2026. While the high-rise overhang provides negotiating power, it also signals intense competition for tenants.
My advice is to focus on transit-oriented developments (TODs) or properties near major employment hubs and universities. Analyse the historical rental rates and occupancy in the specific building you’re considering.
A lower entry price is attractive, but only if it translates into a sustainable positive cash flow after accounting for maintenance fees and other costs.
2. Why do some people say it’s a buyer’s market now?
The term ‘buyer’s market’ is being used because the supply of available properties for sale currently outstrips the number of active, qualified buyers.
This imbalance, confirmed by data from NAPIC showing a significant number of unsold units, shifts the negotiating leverage from the seller to the buyer.
Consequently, buyers are in a stronger position to negotiate prices downwards, request favourable terms, and choose from a wide variety of options without the pressure of competing offers.
3. What should I do if I feel pressured to buy a house now?
You must resist pressure, whether it comes from agents, family, or fear of missing out (FOMO). A property purchase is one of the largest financial decisions you will ever make.
My philosophy is clear: ‘Market movements are a combination of macroeconomic gravity and technical psychology.’ Do not let emotional psychology dictate your actions. Rely on the gravity of data.
If your financial readiness checklist is not fully ticked, or if the numbers for a potential investment do not make sense, the correct action is to wait, continue saving, and monitor the market. A rushed decision is rarely a good one.
4. What are the latest government policies affecting property buyers in Malaysia for 2026?
For 2026, key policies include the stabilised Overnight Policy Rate (OPR) by BNM, which provides clarity on mortgage costs.
Additionally, the government’s push for the new MM2H programme is intended to attract foreign capital, which could selectively boost high-end and tourism-related properties.
Buyers should also monitor announcements regarding stamp duty exemptions for first-time homebuyers, which are often announced during the national budget and can provide significant savings.
Andrew Wong’s Final Thoughts
In conclusion, while macroeconomic indicators suggest that 2026 presents a favourable window for purchasing property in Malaysia, the concept of a ‘good time’ is ultimately relative. The market offers opportunities, but they are not universal across all property types or locations. The most critical variable in the equation is you—the buyer. A financially sound individual with a clear objective and a long-term perspective can succeed even in a challenging market. Conversely, an unprepared buyer can fail even in a boom. Ground your decision in rigorous financial planning and objective data, not in market hype or pressure. That is the only reliable path to a sound investment.
Sources & Methodology
Andrew Wong strictly relies on primary regulatory data and authoritative official information to ensure accuracy. Data cited in this guide is sourced from:
- National Property Information Centre (NAPIC) Malaysia – Property Market Reports
- Bank Negara Malaysia (BNM) – Monetary Policy & OPR Statements
- Official Malaysia My Second Home (MM2H) Programme Portal
- Securities Commission Malaysia (SC) – Regulatory Frameworks
- Investopedia – Financial Definitions and Concepts
*Disclaimer: The content of this article represents the personal views of the author (Andrew Wong) and is for educational and reference purposes only. It does not constitute professional investment or financial advice. Trading and investing involve significant risk; proceed with caution.*
